PMEGP Loan 2026: Gaon Mein Business Shuru Karne Ke Liye Loan Aur Subsidy Kaise Milegi?
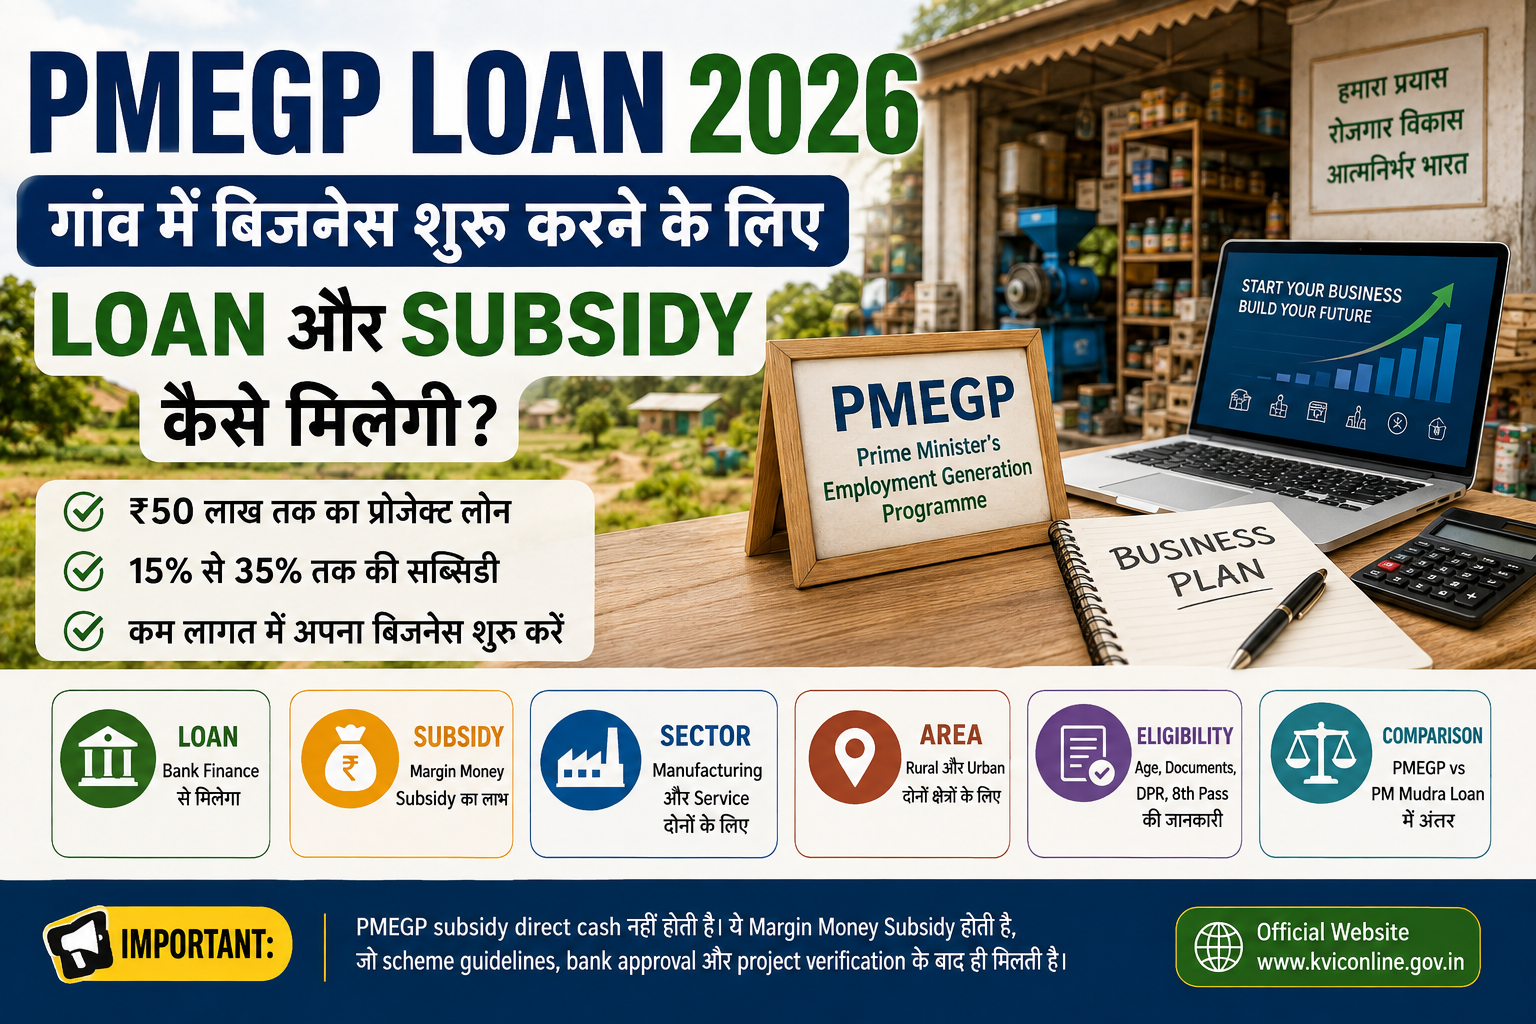
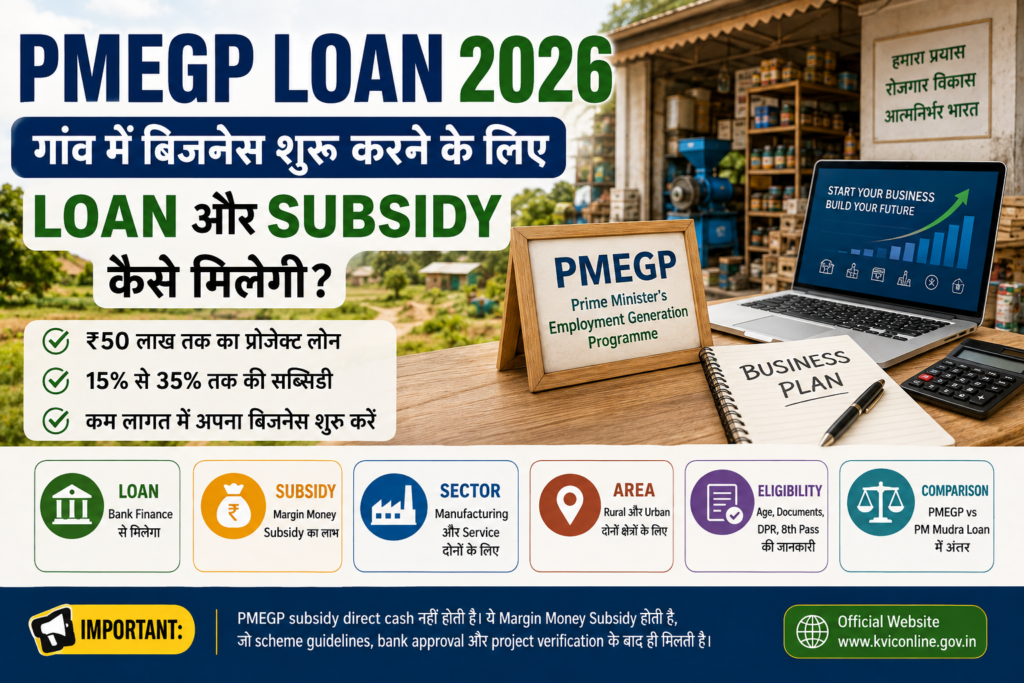
Agar aap gaon ya shahri area mein apna naya business, micro-enterprise ya self-employment venture shuru karna chahte hain, lekin business ke liye paison ki kami hai, to Prime Minister’s Employment Generation Programme (PMEGP) aapke liye ek useful government scheme ho sakti hai.
PMEGP ek credit-linked subsidy scheme hai. Iske through eligible applicants ko bank finance ke saath Margin Money Subsidy ka benefit mil sakta hai. Is scheme ka main objective rural aur urban areas mein naye micro-enterprises establish karke self-employment aur employment opportunities create karna hai.
Is article mein Rural Finance Guide par hum simple language mein samjhenge:
- PMEGP Yojana 2026 kya hai?
- PMEGP mein kitna loan aur subsidy mil sakti hai?
- Manufacturing aur Service/Business sector ki maximum project limit kya hai?
- Rural aur Urban area mein subsidy kitni hai?
- General aur Special Category applicants ke liye kya difference hai?
- 8th pass ki condition kya hai?
- PMEGP ke liye kaun apply kar sakta hai?
- Kaun-se documents chahiye?
- PMEGP online application kaise karein?
- ₹10 lakh ke project mein subsidy aur bank finance ka calculation kaise hota hai?
- PMEGP aur PM Mudra Loan mein kya difference hai?
Important Note: PMEGP ki subsidy direct cash payment nahi hoti. Ye Margin Money Subsidy hoti hai, jo scheme rules aur bank/implementing agency ki approval process ke according handle ki jaati hai. Loan approval bhi automatic ya guaranteed nahi hota.
PMEGP Yojana 2026 Kya Hai?
PMEGP ka full form Prime Minister’s Employment Generation Programme hai. Ye Government of India ki ek credit-linked subsidy scheme hai, jiska objective naye micro-enterprises aur self-employment ventures establish karke employment opportunities create karna hai.
- National Level Implementation: Khadi and Village Industries Commission (KVIC) nodal agency ke roop mein ise implement karta hai.
- State Level Implementation: KVIC State Offices, State KVIBs, District Industries Centres (DICs) aur participating banks ke through implementation process hota hai.
Scheme ka focus sirf loan dena nahi hai. Iska main purpose logon ko productive business activity ke through self-employment ka opportunity dena bhi hai.
PMEGP Ke Main Objectives:
- Rural aur urban areas mein self-employment opportunities create karna.
- Naye micro-enterprises establish karna.
- Traditional artisans aur prospective entrepreneurs ko support karna.
- Rural aur urban unemployed youth ke liye livelihood opportunities create karna.
- Rural areas se employment ke liye hone wale migration ko kam karne mein help karna.
- Local level par sustainable employment generate karna.
Official PMEGP information ke according scheme ka focus new viable micro-enterprises par hai, subject to scheme guidelines aur negative-list conditions.
PMEGP Mein Kitna Loan Aur Subsidy Milti Hai?
PMEGP mein government applicant ko poora project cost free mein nahi deti. Project financing broadly teen parts se milkar banti hai:
$$\text{Total Project Cost} = \text{Applicant Contribution} + \text{Bank Loan Finance} + \text{Margin Money Subsidy}$$
Maximum Admissible Project Cost:
- Manufacturing Sector: ₹50 Lakh tak
- Business / Service Sector: ₹20 Lakh tak
Ye limits Margin Money Subsidy ke liye admissible project cost se related hain. Agar project cost prescribed limit se zyada hai, to excess amount par government subsidy nahi milegi; bank apne lending norms ke according additional finance consider kar sakta hai.
PMEGP Subsidy Rate 2026
PMEGP mein subsidy applicant ki category aur project location ke according change hoti hai.
| Applicant Category | Rural Area Subsidy | Urban Area Subsidy | Own Contribution |
| General Category | 25% | 15% | 10% |
| Special Category (SC, ST, OBC, Minorities, Women, Ex-Servicemen, PwD, NER/Hill/Border Areas) | 35% | 25% | 5% |
₹10 Lakh Project Cost Ka Simple Calculation Example
Maan lijiye aap Rural Area mein ₹10,00,000 (₹10 Lakh) ka project shuru karna chahte hain:
Case A: Agar Aap General Category Mein Hain
- Total Project Cost: ₹10,00,000
- Own Contribution (10%): ₹1,00,000
- Margin Money Subsidy (25%): ₹2,50,000
- Remaining Amount: Bank Finance ke through arrange hoga.
Case B: Agar Aap Special Category Mein Hain
- Total Project Cost: ₹10,00,000
- Own Contribution (5%): ₹50,000
- Margin Money Subsidy (35%): ₹3,50,000
- Remaining Amount: Bank Finance ke through arrange hoga.
Important Note: Iska matlab ye nahi hai ki ₹3.50 lakh subsidy applicant ko cash mein hand-to-hand mil jayegi. Margin Money Subsidy bank ke through scheme mechanism ke according adjust hoti hai.
PMEGP Subsidy Ka Paisa Kaise Kaam Karta Hai?
PMEGP ki subsidy ko Margin Money Subsidy kaha jata hai. Ye normal cash subsidy ki tarah applicant ke savings account mein freely spend karne ke liye transfer nahi hoti.
- Scheme ke mechanism ke according bank subsidy claim karta hai aur applicable conditions ke baad subsidy loan account mein adjust ki jaati hai.
- PMEGP guidelines mein Margin Money ke liye 3-year lock-in period ka provision diya gaya hai.
- Is 3 saal ke dauran prescribed conditions aur physical verification ka process complete kiya jata hai.
Isliye PMEGP ko “free government money” ya “cash gift” samajhna bilkul galat hoga.
PMEGP Mein Kitna Bank Loan Milta Hai?
PMEGP mein applicant ko apni category ke according 5% ya 10% own contribution dena hota hai. Baaki eligible project cost ko bank finance kar sakta hai, subject to:
- Project viability
- Applicant profile
- Bank appraisal & Repayment capacity
- Required documents & Scheme guidelines
- Bank ke internal lending norms
Official guidelines ke according own contribution aur Margin Money Subsidy ke baad balance amount bank loan ke form mein provide karta hai.
PMEGP Ke Liye Kaun Apply Kar Sakta Hai? (Eligibility Criteria)
New enterprise ke liye basic eligibility framework ye hai:
- Age: Applicant ki age kam se kam 18 years honi chahiye.
- Income Ceiling: New PMEGP projects ke liye koi maximum income ceiling nahi hai.
- Educational Qualification (8th Pass Condition):
- Manufacturing sector mein ₹10 Lakh se zyada, ya
- Business/Service sector mein ₹5 Lakh se zyada
- ka project hone par applicant ka minimum VIII (8th) Standard Pass hona required hai.
- New Project Condition: PMEGP ki assistance primary level par NEW Projects ke liye hai. Existing units jo pehle se PMRY, REGP ya kisi other Government scheme ke under established hain, ya jinhone applicable government subsidy already avail ki hai, unki eligibility new-unit subsidy ke under nahi aati.
PMEGP Mein Family Se Kitne Log Apply Kar Sakte Hain?
Ye point bohot zaroori hai. PMEGP guidelines ke according ek family se ek hi person new enterprise ke liye PMEGP financial assistance le sakta hai.
- Guidelines ke anusaar “Family” mein: Self, Spouse (Pati/Patni), aur Unmarried Children include hote hain.
- Isliye husband-wife dono ke naam par same family se alag-alag PMEGP new-unit subsidy claim karna guidelines ke khilaf hai.
PMEGP Mein Kaun-Kaun Se Business Ho Sakte Hain?
PMEGP ka scope kaafi broad hai aur eligible new viable micro-enterprises ko cover karta hai, lekin scheme ki negative list aur activity-specific conditions apply hoti hain.
Possible Eligible Activities:
- Food processing units
- Small manufacturing units
- Repair & service centres
- Furniture-related business
- Garment manufacturing
- Rural industry activities & Processing units
- Certain eligible transport activities & Trading activities
Trading Business Par Loan Ki Condition:
Trading ke liye PMEGP mein specific restrictions hain. Official guidelines ke according specific trading activities hi permitted hain, jaise:
- Specified areas mein sales outlets
- Khadi/Village Industry products ke retail outlets
- PMEGP units ke manufactured products ki direct sale
- Manufacturing/processing/service facility se backed retail outlets
Dhyan Rahein: “Koi bhi normal shop kholkar PMEGP subsidy mil jayegi” aisa assume na karein. Trading activity ke liye exact eligibility official guidelines ke according check karein.
PMEGP Ke Liye Zaroori Documents List
Online application ke time dekhe jaane wale basic documents:
- Aadhaar Card (Verification ke liye)
- PAN Card
- Passport-size Photograph
- Educational Qualification Certificate (8th Pass marksheet, agar applicable ho)
- Special Category / Caste Certificate (Agar applicable ho)
- Detailed Project Report (DPR)
- Bank-related details & Address proof
Detailed Project Report (DPR) Kya Hai Aur Ye Kyun Zaroori Hai?
DPR ka full form Detailed Project Report hota hai. Ye aapke proposed business ki complete blueprint hoti hai. Ek achhi DPR mein following details honi chahiye:
- Business ka naam, activity, aur location
- Total project cost, machinery/equipment cost, aur working capital
- Applicant contribution aur expected bank finance
- Expected employment generation aur raw material details
- Production/service details, expected sales, expenses, aur profitability estimate
Bank isi DPR ke basis par project ki viability aur aapki repayment capacity evaluate karta hai. Isliye PMEGP ke liye realistic DPR bahut important hai.
PMEGP Online Apply Kaise Karein? (Step-by-Step)
PMEGP application official PMEGP e-portal ke through ki jaati hai:
- Step 1: Official KVIC PMEGP Portal par visit karein.
- Step 2: Home page par “Application for New Unit” option select karein.
- Step 3: Basic Personal Details (Name, Address, Identity details, Mobile, Category, Education) enter karein.
- Step 4: Implementing Agency (KVIC / KVIB / DIC) aur preferred financing Bank branch select karein.
- Step 5: Business details (Project cost, machinery expenditure, working capital, employment) fill karein.
- Step 6: Subhi required documents aur Project Report (DPR) scan karke upload karein.
- Step 7: Form cross-check karke Final Submit karein. System se mila Application ID / Reference Number safe save kar lein.
Application Submit Hone Ke Baad Ka Workflow:
$$\text{Online Application} \rightarrow \text{Agency Screening} \rightarrow \text{Bank Appraisal} \rightarrow \text{Loan Sanction} \rightarrow \text{Project Setup} \rightarrow \text{Verification} \rightarrow \text{Subsidy Adjustment}$$
(Dhyan rahe: Online form bharne se loan approval ki guarantee nahi hoti, decision bank appraisal par depend karta hai).
PMEGP Loan Par Interest Rate Aur Repayment Terms
- Interest Rate: PMEGP loan par normal bank lending rates applicable hote hain.
- Repayment Period: Generally 3 se 7 saal ka time milta hai, jisme applicable moratorium period bhi shaamil hota hai.
- Exact EMI, interest rate, aur moratorium terms aapka bank project profile ke basis par decide karta hai.
Kya PMEGP Mein ₹50 Lakh Free Milta Hai?
Nahi. Ye ek bohot badi galatfehmi hai.
- ₹50 Lakh manufacturing sector ki maximum admissible project cost limit hai, koi direct free grant nahi.
- Similarly, Business/Service sector mein limit ₹20 Lakh hai.
- Agar aapka manufacturing project ₹50 Lakh ka hai, toh us par 15% se 35% tak Margin Money Subsidy calculate hoti hai. Baaki amount applicant contribution aur bank loan ke roop mein adjust hota hai.
PMEGP Loan vs PM Mudra Loan (Comparison)
Dono schemes ko lekar logon ko aksar confusion hota hai:
| Feature | PMEGP Scheme | PM Mudra Loan |
| Main Objective | Naye micro-enterprise establish karna | Business credit & working capital dena |
| Government Subsidy | 15% se 35% Margin Money Subsidy | No Margin Money Subsidy |
| New vs Existing | Primary focus NEW Units par hai | New aur Existing business dono eligible hain |
| Manufacturing Limit | ₹50 Lakh tak | Product category norms ke according |
| Service Sector Limit | ₹20 Lakh tak | Product category norms ke according |
| Own Contribution | Category ke according 5% ya 10% | Bank / Product terms ke according |
Gramin kshetra ke doosre social security aur insurance schemes ke baare mein janne ke liye aap hamare PMJJBY Scheme Guide aur PMSBY Scheme Details wale articles bhi padh sakte hain.
PMEGP Mein Second Loan Ka Provision (Upgradation)
Existing PMEGP, REGP, ya MUDRA units ke upgradation aur expansion ke liye second loan ka provision bhi available hai.
- Iske under manufacturing units ke liye ₹1 Crore tak aur service units ke liye ₹25 Lakh tak ka second loan mil sakta hai.
- Condition: First loan ka timely repayment hua ho aur unit profit mein chal rahi ho.
PMEGP Fraud Se Kaise Bachein?
Government schemes ke naam par chal rahe scams se savdhan rahein:
- No Agents: KVIC / DIC ne kisi private middleman ya agent ko sanctioning ke liye appoint nahi kiya hai.
- No Guaranteed Subsidy Claims: “100% Loan Approval Guaranteed” bolne wale logon ko advance paise na dein.
- Keep Details Safe: Apna OTP, UPI PIN, ya Bank passwords kisi ke saath share na karein.
PMEGP 2026: Quick Summary Table
| Parameter | Scheme Details |
| Full Form | Prime Minister’s Employment Generation Programme |
| Nodal Agency | KVIC (Khadi and Village Industries Commission) |
| Max Project Cost (Manufacturing) | ₹50 Lakh |
| Max Project Cost (Service) | ₹20 Lakh |
| Rural Area Subsidy | General: 25% |
| Urban Area Subsidy | General: 15% |
| Own Contribution | General: 10% |
| Minimum Age | 18 Years |
| 8th Pass Rule | Above ₹10L (Mfg) / Above ₹5L (Service) |
Frequently Asked Questions (FAQs)
Q1. PMEGP ka full form kya hai?
PMEGP ka full form Prime Minister’s Employment Generation Programme hai.
Q2. PMEGP mein maximum kitna project bana sakte hain?
Manufacturing sector mein ₹50 Lakh aur Business/Service sector mein ₹20 Lakh tak ka project margin money subsidy ke liye admissible hai.
Q3. Kya PMEGP mein ₹50 lakh free milta hai?
Nahi, ye maximum project cost ceiling hai. Free cash grant nahi milta.
Q4. Rural area mein PMEGP subsidy kitni hai?
General Category ke liye 25% aur Special Category ke liye 35% Margin Money Subsidy hai.
Q5. PMEGP ke liye minimum age kya hai?
Applicant ki age kam se kam 18 saal honi chahiye.
Q6. Kya PMEGP mein income ceiling hai?
Naye projects ke liye koi maximum income limit nahi hai.
Q7. Kya 8th pass hona compulsory hai?
Manufacturing mein ₹10 Lakh se bada aur Service mein ₹5 Lakh se bada project hone par hi 8th pass certificate zaroori hai.
Q8. Kya existing business PMEGP ka benefit le sakta hai?
New unit subsidy nahi milti, par eligible units second loan / upgradation scheme ke liye apply kar sakti hain.
Q9. Loan repayment period kitna hota hai?
Repayment period generally 3 se 7 saal ka hota hai.
Q10. Online application kahan se karein?
Official PMEGP Online Portal se online application karein.
Conclusion & Official Sources
PMEGP Yojana 2026 gaon aur shahar dono jagah naya business shuru karne wale youth ke liye ek behtareen credit-linked subsidy programme hai. Sahi DPR, realistic business plan, aur official portal se application submit karke aap iska poora fayda utha sakte hain.
- Official Website: KVIC PMEGP Official Portal
- Ministry Source: Ministry of MSME, Govt of India
Disclaimer: Rural Finance Guide ek educational informational website hai. PMEGP rules, eligibility, aur banking terms time ke saath update ho sakte hain. Application submission se pehle official KVIC portal se details zaroor verify karein.